• Link to Facebook
  • Link to X
  • Link to Instagram
  • Link to LinkedIn
800 222 8711| Contact Us| Submit a Claim| Pay My Bill| Client Portal
Murphy Insurance
  • Get A Quote
    • Auto Insurance Quote
    • Homeowners Quote
    • Condominium Quote
    • Renters Insurance Quote
    • Umbrella Liability Quote
    • Boat Insurance Quote
    • Valuables Coverage Quote
    • Life Insurance Quote
    • Term Life Insurance Quote – Instant
    • Disability Insurance Quote
    • Long-Term Care Quote
    • Business Insurance Quote
    • Employee Benefits Quote
    • Other Insurance Quote
  • Personal
    • Overview
    • Auto Insurance
      • Overview
      • Auto Insurance Discounts
      • Auto Insurance Coverage Options
      • Auto Insurance Rating Factors
      • Change of Garaging
      • Registry Service
    • Motorcycle Insurance
    • Recreational Vehicle Insurance
    • Homeowners Insurance
      • Overview
      • Earthquake Insurance
      • Mobile Home Insurance
      • Homeowner’s Manual
    • Condominium Insurance
      • Condo Owner’s Manual
    • Renters Insurance
    • Personal Umbrella Insurance
    • Flood Insurance
    • Boat Insurance
    • Financial Insurance
    • Life Insurance
    • Term Life Insurance
    • Disability Insurance
    • Long-Term Care Insurance
    • Event & Specialized Insurance
      • Event Insurance
      • Wedding Insurance
  • Business
    • Overview
    • Commercial Property Insurance
      • Commercial Package Policy
      • Business Owner Policy
      • Business Interruption Insurance 
      • Ordinance or Law
    • Business Liability Insurance
    • Commercial Auto Insurance
    • Workers’ Compensation Insurance
    • Business Insurance Bonds
    • Employee Benefits
      • Group Health Insurance
      • Group Dental Insurance
      • Group Life, Disability & Long-Term Care Insurance
      • Voluntary Employee Benefits
    • Business Continuation Planning
    • Industry Specialties
      • Antique Dealer Insurance
      • Banking & Financial Institution Insurance
      • Contractor Insurance
      • Construction Insurance
      • Farm & Agriculture Insurance
      • Manufacturing Insurance
      • Restaurant Insurance
      • Religious Institution Insurance
      • Solar Contractor Insurance
      • Technology Business Insurance
    • Business Spotlight Series
  • Resources
    • Overview
    • Business Spotlight Series
    • Claims Center
    • Certificate of Insurance Request
    • Condominium Owner’s Manual
    • FAQs (Frequently Asked Questions)
    • Forms Center
    • Insurance Tips
    • Helpful Links
    • Homeowner’s Manual
    • Insurance Companies
    • Insurance Myths
    • Murphy Insurance 24 | Client Portal
    • Pay My Bill
  • Blog
  • About
    • Why Choose Us?
    • Locations
      • Bolton, MA Office
      • Groton, MA Office
      • Harvard, MA Office
      • Hudson, MA Office
      • Marlborough, MA Office
      • Medway, MA Office
    • Careers
      • Business Sales Executive
      • Financial Insurance Manager
      • Personal Acct Mgr – Hudson
    • Communities Served
    • Meet the Team
    • Our Values
    • We’re A Five Star Agency
    • Trusted Choice Agency
    • Donation and Sponsorship Requests
    • Customer Reviews
    • Share A Review Of Us
  • Contact
  • Click to open the search input field Click to open the search input field Search
  • Menu Menu
  • Home Page
  • Contact Us
  • Locations
  • Get A Quote
  • Claims Center
  • Personal Insurance
  • Business Insurance
  • Certificate of Insurance Request
  • About Us
  • Careers
  • Blog
  • Resources
  • Pay My Bill
  • Forms Center
  • Murphy Insurance 24 | Client Portal
  • Auto Insurance
  • Homeowners Insurance
  • Renters Insurance
  • Share a Review
You are here: Home1 / Blog2 / Business Insurance3 / Five Strategies for Reducing Workers’ Compensation Costs

Five Strategies for Reducing Workers’ Compensation Costs

November 17, 2025|byMurphy Insurance|inBusiness Insurance|business insurance, commercial insurance, osha, worker compensation insurance, workers comp, workers compensation, workplace safety

When a company experiences significant increases in workers’ compensation costs, it often triggers internal initiatives aimed at reducing insurance costs and spending.

The key to spending fewer dollars is more than just stopping a few accidents; it is having a sound safety program designed to continuously improve and prevent additional accidents.
Safety Goggles 1200
Click here to submit an inquiry to Murphy Insurance or call us at 800 222 8711

Building an effective company safety program that, at a minimum, complies with Occupational Safety and Health Administration (OSHA) standards can yield significant savings for a business by reducing injuries and illnesses and saving workers’ compensation dollars.

Building a Solid OSHA Program

There are five basic steps a business can take to build a well-rounded safety program that produces a safe work environment, meets OSHA requirements, reduces accidents, and ultimately reduces workers’ compensation costs.

  1. Develop the various programs required by the OSHA standards.
  2. Integrate those programs into the daily operations.
  3. Investigate all injuries and illnesses.
  4. Provide training to develop safety competence in all employees.
  5. Audit your programs and your work areas on a regular basis to stimulate continuous improvement.

Develop Programs Required by OSHA Standards

Aside from being a requirement for general industry, OSHA standards provide a good pathway to reducing incidents. A good number of accidents stem from poorly developed or poorly implemented OSHA programs: failure to keep walking and working surfaces clear may result in slips or trips, not using personal protective equipment may result in excessive lacerations, and poor lifting techniques can result in strains.

Many of the OSHA standards require some type of written program to be developed and then communicated to employees. Experience shows that companies with thoroughly developed OSHA-compliant programs have fewer accidents, more productive employees and lower workers’ compensation costs.

Integrate Programs into Daily Operations

Policies alone won’t get results; the program must move from paper to practice in order to succeed. Putting a policy into practice requires a strategic plan clearly communicated to key participants, good execution of that plan based on developed competencies and a culture that inspires and rewards people to do their best.

When developing any business initiative, there must be an emphasis on frontline supervisors and helping them succeed. Every good business person knows that any new program, whether it is safety, quality, or anything else, lives and dies with the frontline supervisor. If the frontline supervisor knows the program and wants to make it happen, the program succeeds; if not, it becomes a constant struggle and an endless drain on resources and energy. Providing supervisors with knowledge and skills through training is critical to the success of any program.

A solid OSHA program, integrated into daily operations and led by competent supervisors, is just the beginning. Successful safety programs focus on being proactive instead of always reacting to issues. Accident investigations provide an excellent source of information on real or potential issues present in the workplace.

Investigate All Injuries and Illnesses

Workers’ compensation is designed to recompense employees for injuries or illnesses they suffer in the course of their employment. This should not come as a surprise, but increasing numbers of claims drive up workers’ compensation costs. To reduce those costs, you must simply reduce your accidents, and the ability to do so is significantly enhanced when those accidents are fully investigated rather than simply reported.

Accident reports are historical records that cite facts, while accident investigations delve deeper to identify the root cause and make improvements. Businesses that stop rising workers’ compensation costs have an effective accident investigation process that discovers the root cause of the problem. Unless the root cause is discovered, recommendations for improvement will remain fruitless. Again, training proves beneficial because a supervisor skilled in incident analysis is a better problem solver for all types of production-related issues, not just safety.

All accidents should be investigated to find out what went wrong and why. Some may suggest investigating every accident is a bit over the top, and only those that incur significant costs are worthy of scrutiny. But ask yourself this question: If you only investigated serious quality concerns instead of every little deviation, would your quality program still be effective? Companies with solid quality programs investigate and resolve every deviation from quality standards.

If your emphasis is only on those incidents that have to be recorded on the OSHA 300 log, you close your eyes to the biggest accident category: first aid-only incidents. Many companies get upset about recordables or lost-time accidents because of the significant costs involved, but they don’t realize that the small costs and high numbers of first-aid-only incidents really add up.

Statistics show that for every 100 accidents, 10 will be recordable and one will be a lost-time incident. If you investigate only recordable or lost-time accidents, 89 accidents go unnoticed. Would you consider a quality program successful if it had an 89% failure rate? Reducing serious accidents means you must reduce your overall rate of all accidents – including first aid-only incidents. That only happens when every incident is fully investigated to identify the root cause, and remedial actions are identified and integrated into daily operations.

Training and Auditing for Continuous Improvement

The final steps focus on training and auditing your program for continuous improvement. Training plays a significant role in safety and in reducing workers’ compensation costs. The goal of training is to develop competent people who have the knowledge, skill and understanding to perform assigned job responsibilities. Competence, more than anything else, will improve all aspects of your business and drive down costs. Supervisors must have the knowledge and ability to integrate every safety program into their specific areas of responsibility. Every employee must know what is expected of them when it comes to implementing safe work procedures. Once the programs are developed and implemented, they must be reviewed regularly to ensure they remain relevant and effective.

This might require a significant change in how you manage your safety program, but if your workers’ compensation rates are high, it may be time to make this leap.

Tangible Benefits

  1. Studies indicate there is a return on investment and that companies see direct bottom-line benefits with a properly designed, implemented and integrated safety program.
  2. A competency-based safety program is compliant with OSHA requirements and therefore reduces the threat of OSHA fines.
  3. A competency-based safety program lowers accidents, and fewer accidents lower workers’ compensation costs. When incidents do occur, a competency-based safety program fully evaluates the issue, identifies the root cause to prevent recurrence, and provides a workplace free from recognized hazards.
  4. A safer workplace creates better morale and improves employee retention. Auditing keeps your programs fresh and effective, driving continuous improvement.
  5. A competency-based program produces people who are fully engaged in every aspect of their job and are satisfied and fulfilled, producing high-quality goods and services.

How Can We Assist You?

Reducing workers’ compensation costs takes strategy, planning, and the right resources. By focusing on safety, training, and proactive risk management, businesses can make a real impact on their bottom line. Murphy Insurance Agency can connect you with tools, programs, and expert resources to support these strategies, helping keep your team safe, claims low, and your business thriving.

Note: This Workers’ Compensation information is not intended to be exhaustive, nor should any discussion or opinions be construed as legal advice. Readers should contact an appropriate professional for guidance for their specific situation and needs. 
Read Our Workers Comp Posts

Workers’ Comp 101 for Massachusetts Employers

Workers’ Comp 101 for Massachusetts Employers

June 25, 2026
Workers’ compensation rules in Massachusetts are strict and sometimes misunderstood. Learn who must carry coverage, common exemptions, audit triggers, and costly compliance mistakes employers should avoid.
Read more
https://www.dfmurphy.com/wp-content/uploads/Workers-Comp-101-for-Massachusetts-Employers-.jpg 629 1200 Murphy Insurance https://dfmurphy.wpenginepowered.com/wp-content/uploads/Murphy-Insurance-Logo-Header.jpg Murphy Insurance2026-06-25 07:00:272026-06-19 09:18:49Workers’ Comp 101 for Massachusetts Employers
Business Insurance Issues 1200

10 Insurance Issues Businesses Should Keep Top of Mind in 2026

January 7, 2026
Staying ahead of evolving risks is essential for every business in 2026. From property valuations to cyber threats and liability coverage, these 10 insurance considerations can help you safeguard your operations and plan for the unexpected.
Read more
https://www.dfmurphy.com/wp-content/uploads/Business-Insurance-Issues-1200.jpg 628 1200 Dave Schofield https://dfmurphy.wpenginepowered.com/wp-content/uploads/Murphy-Insurance-Logo-Header.jpg Dave Schofield2026-01-07 09:00:062026-01-16 09:26:2510 Insurance Issues Businesses Should Keep Top of Mind in 2026
Plan a Safer Workplace With the 2026 National Safety Observances Calendar

Plan a Safer Workplace With the 2026 National Safety Observances Calendar

January 6, 2026
Build a stronger safety culture with our 2026 National Safety Observances Calendar, a simple planning tool to keep workplace safety top of mind all year. The downloadable PDF includes key observance dates, plus training and awareness resources to help reduce accidents, improve productivity, and lower insurance costs.
Read more
https://www.dfmurphy.com/wp-content/uploads/Plan-a-Safer-Workplace-With-the-2026-National-Safety-Observances-Calendar.jpg 628 1200 Murphy Insurance https://dfmurphy.wpenginepowered.com/wp-content/uploads/Murphy-Insurance-Logo-Header.jpg Murphy Insurance2026-01-06 09:00:092026-01-16 09:31:41Plan a Safer Workplace With the 2026 National Safety Observances Calendar
Safety Goggles 1200

Five Strategies for Reducing Workers’ Compensation Costs

November 17, 2025
Saving money on workers’ compensation premiums goes beyond preventing a few accidents—it starts with a strong safety program that focuses on continuous improvement. A program that meets or exceeds OSHA standards can help reduce injuries and illnesses, ultimately lowering workers’ compensation costs and protecting your team.
Read more
https://www.dfmurphy.com/wp-content/uploads/Safety-Goggles-1200.jpg 628 1200 Murphy Insurance https://dfmurphy.wpenginepowered.com/wp-content/uploads/Murphy-Insurance-Logo-Header.jpg Murphy Insurance2025-11-17 16:26:292025-11-17 21:36:32Five Strategies for Reducing Workers’ Compensation Costs
Updated Hazard Communication Standard

Updated Hazard Communication Standard from OSHA

July 29, 2025
Employers should review OSHA's the final rule on its Hazard Communication Standard (HCS) to determine how the changes affect them. Specifically, paying attention to their compliance dates for required actions which go into affect in 2026 and 2027.
Read more
https://www.dfmurphy.com/wp-content/uploads/Updated-Hazard-Communication-Standard.jpg 628 1200 Murphy Insurance https://dfmurphy.wpenginepowered.com/wp-content/uploads/Murphy-Insurance-Logo-Header.jpg Murphy Insurance2025-07-29 08:46:522025-08-15 10:13:47Updated Hazard Communication Standard from OSHA
Person working

I’m self-employed and don’t have employees—Workers’ Comp Coverage isn’t available | Insurance Myths
May 30, 2025
In the past, self-employed individuals without employees couldn’t access Workers’ Compensation insurance. But now, many states allow you to purchase coverage even if you’re a one-person operation. This shift reflects the growing recognition of the risks self-employed individuals face and the need for financial protection. Even if you’re a solo entrepreneur, freelancer, or independent contractor, Workers’ Compensation coverage is available to you—and in many cases, it’s a smart investment in your personal and professional safety.
Read more
https://www.dfmurphy.com/wp-content/uploads/Person-working-ex-1200.jpg 628 1200 Murphy Insurance https://dfmurphy.wpenginepowered.com/wp-content/uploads/Murphy-Insurance-Logo-Header.jpg Murphy Insurance2025-05-30 13:56:352025-06-02 13:08:21I’m self-employed and don’t have employees—Workers’ Comp Coverage isn’t available | Insurance Myths
Person working

I’m self-employed and don’t have employees—I don’t need Workers’ Comp Coverage | Insurance Myths

May 15, 2025
As a self-employed business owner, you’ve probably heard the myth—or maybe even told yourself—“I don’t need Workers’ Compensation insurance because I don’t have employees.” On the surface, it makes sense: no staff, no payroll, no legal requirement for coverage. But here’s the truth...Even if you’re the only person on the job, you’re still at risk—and Workers’ Comp can protect you.
Read more
https://www.dfmurphy.com/wp-content/uploads/Person-working-2-Myth-16-1200.jpg 628 1200 Murphy Insurance https://dfmurphy.wpenginepowered.com/wp-content/uploads/Murphy-Insurance-Logo-Header.jpg Murphy Insurance2025-05-15 14:26:232025-06-02 13:09:42I’m self-employed and don’t have employees—I don’t need Workers’ Comp Coverage | Insurance Myths
Happy co-workers

Fostering a Culture of Workplace Safety

December 18, 2024
Fostering a strong safety culture provides many benefits to an organization. This article explains what it means to have a strong safety culture, outlines associated benefits and provides strategies small businesses can implement to establish this type of culture.
Read more
https://www.dfmurphy.com/wp-content/uploads/Happy-co-workers-scaled.jpg 1340 2560 Murphy Insurance https://dfmurphy.wpenginepowered.com/wp-content/uploads/Murphy-Insurance-Logo-Header.jpg Murphy Insurance2024-12-18 12:56:062025-04-01 13:59:28Fostering a Culture of Workplace Safety
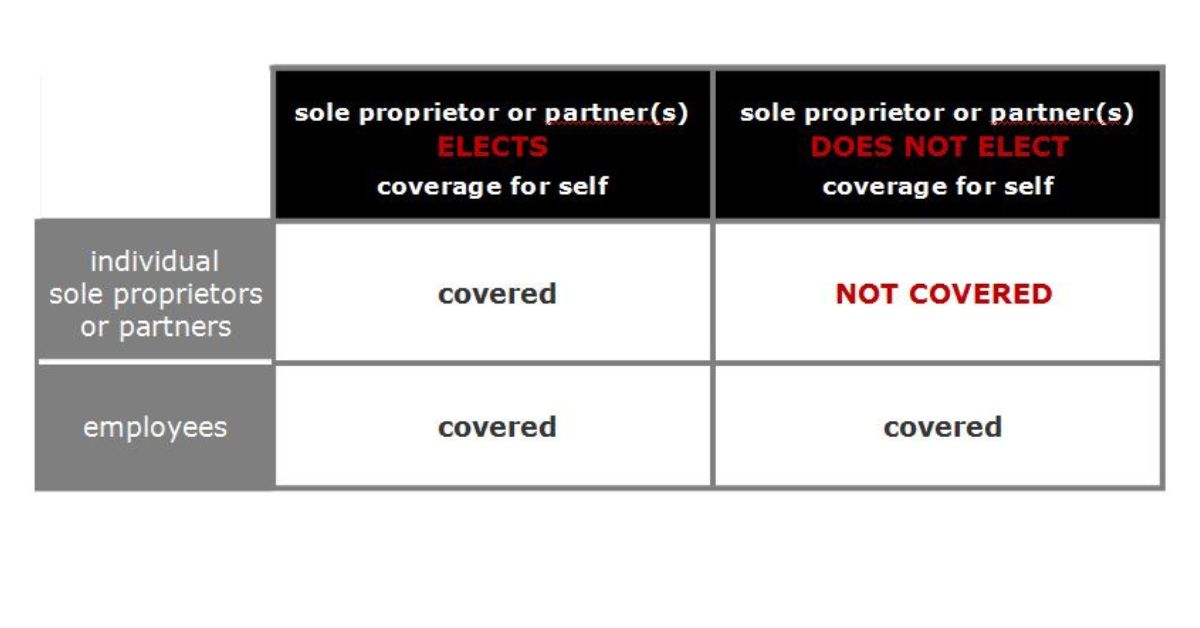
Sole Proprietors and Partners Not Always Covered by Workers' Comp

Sole Proprietors and Partners Not Always Covered by Workers’ Comp

March 29, 2024
Ensure you know the situation: Sole Proprietors and Partnerships must elect proper insurance coverage to safeguard themselves. Don't overlook this crucial protection – it's your livelihood at stake. For other businesses, verify coverage status to avoid potential premium hikes in audits.
Read more
https://www.dfmurphy.com/wp-content/uploads/Untitled-design-154.jpg 628 1200 Murphy Insurance https://dfmurphy.wpenginepowered.com/wp-content/uploads/Murphy-Insurance-Logo-Header.jpg Murphy Insurance2024-03-29 09:00:002024-08-20 11:54:26Sole Proprietors and Partners Not Always Covered by Workers’ Comp
Previous Previous Previous Next Next Next

Visit Our Business Insurance Page

Business Insurance

Murphy Insurance stands as your steadfast partner in safeguarding your business from unforeseen challenges in today’s dynamic business landscape. In an era where comprehensive business insurance is not just a prudent choice but a vital one for ensuring the long-term stability and security of your enterprise, we are here to offer our expertise. Running a business inherently entails various risks that can potentially impact your financial stability and reputation. Learn more about our comprehensive business insurance solutions, which are meticulously designed to protect you from these potential threats, granting you peace of mind necessary to focus on the growth and prosperity of your business.

Search Our Site

Search Search

Recent Posts

  • Pest Prevention | Homeowner’s Manual Blog Series September 10, 2026
  • Murphy Insurance Welcomes Evan Macedo to Our Leadership Team September 9, 2026
  • The Value of Using a Virtual Private Network September 1, 2026
  • Should You Put Your Teen on Your Car Policy or Get Them Their Own? August 25, 2026
  • Cybersecurity Essentials | Password Management Best Practices August 20, 2026
  • Electrical Safety | Homeowner’s Manual Blog Series August 17, 2026
  • Your Guide to Fall Festivals in MetroWest Massachusetts and Beyond (2026) August 14, 2026
  • Home Inventory Made Simple | The 30-Minute Method That Helps Claims Go Faster August 13, 2026
  • The Time Is Now to Kick-start Open Enrollment Efforts August 10, 2026
  • Gaining Real-World Business Experience Through Assabet Valley’s Co-op Program August 6, 2026
  • Do College Students Need Renters Insurance? August 3, 2026
  • Certificates of Insurance: The Costly Mistakes Many Businesses Don’t Catch July 30, 2026
  • 5 Ways to Stay Cool Under Summer Pressure July 24, 2026
  • Safe Internet Browsing Practices July 21, 2026
  • Massachusetts Launches 2026 Low-Number License Plate Lottery With 237 Plates Up for Grabs July 15, 2026
  • Business Interruption Insurance: The Coverage That Keeps Your Business Alive When You Can’t Open Your Doors July 14, 2026
  • Outdoor Maintenance | Homeowner’s Manual Blog Series July 9, 2026
  • A Safer Start to Summer: Simple Habits for a Fun and Worry-Free Fourth of July July 1, 2026
  • What Counts as a Home-Based Business (and When Your Home Policy Isn’t Enough) June 30, 2026
  • Workers’ Comp 101 for Massachusetts Employers June 25, 2026
  • Why Disaster Planning Matters: Protecting Your Business from Supply Chain Disruptions June 22, 2026
  • Tropical Storm Arthur—a Reminder That Hurricane Season Has Begun June 18, 2026
  • What to Do When Your Home Insurance Company Requires Repairs June 16, 2026
  • Swimming Pool Safety | Homeowner’s Manual Blog Series June 11, 2026
  • Cyber Insurance for Small Businesses | What It Actually Covers and What It Does Not June 8, 2026

Blog Posts By Category

  • Auto Insurance (31)
  • Business Insurance (213)
  • Community (13)
  • Condominium Insurance (3)
  • Homeowners Insurance (35)
  • Personal Insurance (401)
  • Renters Insurance (9)

Blog Posts by Topic

auto auto accident auto insurance business business insurance car insurance claims commercial auto insurance commercial insurance condo insurance cyber liability insurance deductibles driving safety driving tips fire safety flood insurance general business insurance general safety holiday travel home home insurance home maintenance homeowners insurance home repairs home safety home tips house safety tips hurricane season liability insurance life insurance murphy insurance personal insurance personal liability personal umbrella policy premiums property damage renters insurance rmv road rules road safety safety Small Business Tips winter workers comp workers compensation insurance

Contact Us

  • Contact Us
  • toll-free: 800 222 8711
  • Bolton, MA: 978 779 5566
  • Groton, MA: 978 448 3900
  • Harvard, MA: 978 772 0070
  • Hudson, MA: 978 568 8711
  • Marlborough, MA: 508 485 8211
  • Medway, MA: 508 422 9277
  • Opt-out preferences
  • Disclaimer

Communities

Murphy Insurance Agency provides insurance solutions across Massachusetts and New England. Where you live is not a barrier to our assisting you. We are proud to serve the communities where our customers live and work, including Acton, Ashland, Ayer, Bellingham, Berlin, Blackstone, Bolton, Boston, Boxborough, Boylston, Chelmsford, Clinton, Concord, Devens, Dunstable, Fitchburg, Foxborough, Framingham, Franklin, Groton, Harvard, Holliston, Hopedale, Hopkinton, Hudson, Lancaster, Leominster, Littleton, Lunenburg, Marlborough, Maynard, Medfield, Medway, Mendon, Milford, Millis, Millville, Natick, Norfolk, Northborough, Northbridge, Pepperell, Sherborn, Shirley, Shrewsbury, Southborough, Sterling, Stow, Sudbury, Townsend, Upton, Uxbridge, Wayland, Westborough, Westford, Weston, Whitinsville, Worcester, and last but not least, Wrentham.

About Us

  • Overview
  • Why Choose Us?
  • Locations
  • Careers
  • Communities Served
  • Meet Our Team
  • Our Values
  • Trusted Choice Agency
  • We’re A Five Star Agency
  • Customer Reviews
  • Share a Review of Us
  • Your Opinion Matters

Get A Quote

  • Quote Overview
  • Auto Insurance Quote
  • Homeowners Insurance Quote
  • Condominium Insurance Quote
  • Renters Insurance Quote
  • Umbrella Liability Quote
  • Valuables Coverage Quote
  • Boat Insurance Quote
  • Business Insurance Quote
  • Employee Benefits Quote
  • Life Insurance Quote
  • Term Life Insurance Quote – Instant
  • Disability Insurance Quote
  • Long-Term Care Insurance Quote
  • Other Insurance Quote

Resources

  • Overview
  • Business Spotlight Series
  • Certificate of Insurance Request
  • Claims Center
  • Client Portal
  • Condominium Owner’s Manual
  • FAQs (Frequently Asked Questions)
  • Forms Center
  • Helpful Links
  • Homeowner’s Manual
  • Insurance Companies
  • Insurance Myths
  • Insurance Tips
  • Pay My Bill

Personal Insurance

  • Overview
  • Auto Insurance
  • Motorcycle Insurance
  • Homeowners Insurance
  • Condominium Insurance
  • Renters Insurance
  • Flood Insurance
  • Personal Umbrella Insurance
  • Boat Insurance
  • Recreational Vehicle Insurance
  • Financial Insurance
  • Life Insurance
  • Term Life Insurance
  • Disability Insurance
  • Long-Term Care Insurance

Business Insurance

  • Overview
  • Business Continuation Planning
  • Business Insurance Bonds
  • Business Liability Insurance
  • Business Owner Policy
  • Business Spotlight Series
  • Commercial Auto Insurance
  • Commercial Package Policy
  • Commercial Property Insurance
  • Employee Benefits
  • Industry Specialties
  • Workers’ Compensation Insurance

Legal

  • Accessibility Statement
  • Privacy Policy
  • Terms and Conditions of Use
  • Site Map

Read Our Blog

See all our posts

Recent Posts

  • Pest Prevention | Homeowner’s Manual Blog Series September 10, 2026
  • Murphy Insurance Welcomes Evan Macedo to Our Leadership Team September 9, 2026
  • The Value of Using a Virtual Private Network September 1, 2026
  • Should You Put Your Teen on Your Car Policy or Get Them Their Own? August 25, 2026
  • Cybersecurity Essentials | Password Management Best Practices August 20, 2026
  • Electrical Safety | Homeowner’s Manual Blog Series August 17, 2026
  • Your Guide to Fall Festivals in MetroWest Massachusetts and Beyond (2026) August 14, 2026
  • Home Inventory Made Simple | The 30-Minute Method That Helps Claims Go Faster August 13, 2026
  • The Time Is Now to Kick-start Open Enrollment Efforts August 10, 2026
  • Gaining Real-World Business Experience Through Assabet Valley’s Co-op Program August 6, 2026
  • Do College Students Need Renters Insurance? August 3, 2026
  • Certificates of Insurance: The Costly Mistakes Many Businesses Don’t Catch July 30, 2026
  • 5 Ways to Stay Cool Under Summer Pressure July 24, 2026
  • Safe Internet Browsing Practices July 21, 2026
  • Massachusetts Launches 2026 Low-Number License Plate Lottery With 237 Plates Up for Grabs July 15, 2026
© Copyright 2026 D. F. Murphy Insurance 50 Main Street Hudson, MA 01749 (800) 222-8711 | Website Designed by Elbow Grease Marketing
  • Link to Facebook
  • Link to X
  • Link to Instagram
  • Link to LinkedIn
Link to: On the Road Alone: Essential Safety Tips for Long Solo Drives Link to: On the Road Alone: Essential Safety Tips for Long Solo Drives On the Road Alone: Essential Safety Tips for Long Solo DrivesDriver 1200 (1) Link to: Thanksgiving Kitchen Safety Tips to Keep Your Holiday Safe and Stress-Free Link to: Thanksgiving Kitchen Safety Tips to Keep Your Holiday Safe and Stress-Free Thanksgiving Kitchen Safety Tips to Keep Your Holiday Safe and Stress-FreeThanksgiving Kitchen Safety Tips to Keep Your Holiday Safe and Stress-Free
Scroll to top Scroll to top Scroll to top
Manage Consent
To provide the best experiences, we use technologies like cookies to store and/or access device information. Consenting to these technologies will allow us to process data such as browsing behavior or unique IDs on this site. Not consenting or withdrawing consent, may adversely affect certain features and functions.
Functional Always active
The technical storage or access is strictly necessary for the legitimate purpose of enabling the use of a specific service explicitly requested by the subscriber or user, or for the sole purpose of carrying out the transmission of a communication over an electronic communications network.
Preferences
The technical storage or access is necessary for the legitimate purpose of storing preferences that are not requested by the subscriber or user.
Statistics
The technical storage or access that is used exclusively for statistical purposes. The technical storage or access that is used exclusively for anonymous statistical purposes. Without a subpoena, voluntary compliance on the part of your Internet Service Provider, or additional records from a third party, information stored or retrieved for this purpose alone cannot usually be used to identify you.
Marketing
The technical storage or access is required to create user profiles to send advertising, or to track the user on a website or across several websites for similar marketing purposes.
  • Manage options
  • Manage services
  • Manage {vendor_count} vendors
  • Read more about these purposes
View preferences
  • {title}
  • {title}
  • {title}