
As organizations rapidly adopt artificial intelligence (AI) to improve efficiency and stay competitive, they may become increasingly vulnerable to cyberattacks, including deepfake fraud and AI-enabled phishing.
At the same time, AI’s rapid expansion is prompting cyber insurers to reassess whether existing policy frameworks adequately address these risks.
Although the commercial insurance market has yet to reach consensus on addressing AI-driven threats, many insurers are increasing scrutiny at renewal, which may lead to tighter underwriting standards, additional application questions about AI use, or more explicit exclusions.
Most Cyber Policies Were Not Built for AI
Traditional cyber insurance policies were drafted before AI became mainstream, meaning many neither clearly affirm nor explicitly exclude coverage for AI-related losses, often referred to as silent AI exposure. While such legacy wording, when read broadly, may suggest that AI-related risks are covered, this ambiguity can create uncertainty. For example, risks such as inaccurate AI-generated outputs and AI system manipulation (e.g., data poisoning) may not cleanly align with traditional cyber policy triggers, potentially creating coverage gaps. As AI-related claims begin to surface, insurers are gaining a clearer view of how coverage responds in practice, and reliance on broad interpretation may give way to more explicit policy wording and clearer underwriting.
Why Insurers Are Paying Attention Now
AI is expanding both cyber and liability exposures in ways that are difficult to price. For instance, cybercriminals are using agentic AI to craft sophisticated social engineering scams at scale, while AI-generated voices enable deepfake fraud that is increasingly difficult to distinguish from legitimate communications. Additional exposures include AI-generated errors, regulatory scrutiny and intellectual property concerns. Yet, historical loss data on AI-specific incidents is limited, making it difficult for insurers to assess how frequently such events may occur, their potential severity and the risk of systemic losses.
Regardless, early market responses are already emerging. The Insurance Services Office recently introduced general liability endorsements carriers can use to exclude losses arising from generative AI, and similar concepts could eventually influence wording changes in cyber and technology errors and omissions (E&O) policies.
How Cyber Policy Language Is Changing
Although cyber insurers have generally been slower than some other liability lines to introduce explicit AI-related wording, this is changing. Insurers are taking steps to clarify the extent to which AI-driven events fall within cyber policy triggers, and policy language is evolving to address areas such as deepfake fraud, AI-related regulatory exposure, and IP and copyright risks. Some insurers are narrowing coverage, while others are introducing affirmative grants for specific AI-related risks, such as data poisoning and liability arising from AI-generated outputs. Additionally, a small number of standalone AI insurance products are entering the market. However, these may overlap with existing cyber and tech E&O coverage, as traditional policies may already cover some AI-related risks (e.g., data misuse and system failures).
The Definitional Challenge
Across the insurance market, there is currently no consistent definition of “AI.” Insurers may be reluctant to define AI too narrowly, given the pace of technological development, while overly broad definitions could result in claim denials where AI played only a minor role. Broadly drafted exclusions may also extend beyond a company’s own AI systems to include third-party platforms, which may be problematic given the widespread use of AI among businesses.
Although broad blanket AI exclusions are not yet widespread, this definitional uncertainty means insureds may face questions about their AI use at renewal as insurers seek to better understand emerging exposures.
What Brokers and Insureds Should Do
Brokers and insureds should work together to carefully review renewal policies and endorsement schedules, paying particular attention to terms such as “machine learning,” “automated output,” and “generative.” They should also coordinate a review of cyber, technology E&O, and management liability policies to identify potential coverage gaps or overlaps. Engaging with carriers to confirm specifically whether AI-related losses are covered, excluded or subject to limitations is essential.
As renewal approaches, organizations should map their AI use to better understand their exposures. They should also document how AI is being used, monitored and controlled, as governance frameworks and risk management practices are becoming increasingly important to underwriters. Contact Murphy Insurance Agency to find out more.
https://www.dfmurphy.com/wp-content/uploads/How-AI-Is-Changing-Cyber-Insurance-1200.jpg
628
1200
Wayne Texeira
https://dfmurphy.wpenginepowered.com/wp-content/uploads/Murphy-Insurance-Logo-Header.jpg
Wayne Texeira2026-09-15 07:00:112026-09-17 12:12:48How AI Is Changing Cyber Insurance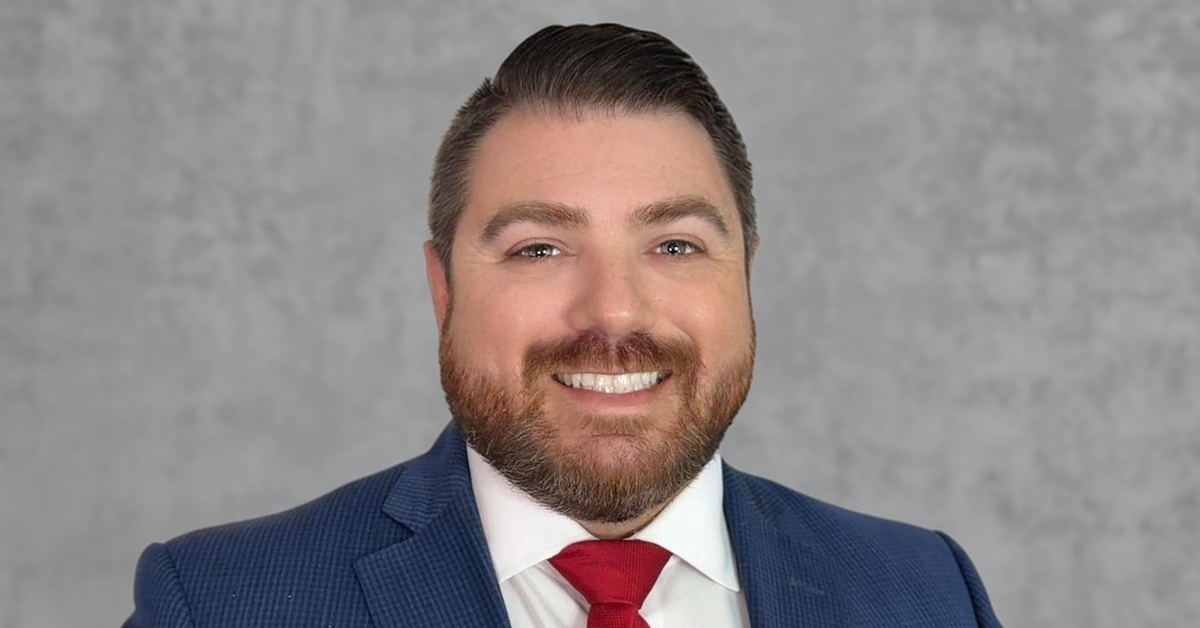 https://www.dfmurphy.com/wp-content/uploads/Evan-Macedo-1200-x-628-.jpg
628
1200
Wayne Texeira
https://dfmurphy.wpenginepowered.com/wp-content/uploads/Murphy-Insurance-Logo-Header.jpg
Wayne Texeira2026-09-09 11:19:362026-09-10 15:39:23Murphy Insurance Welcomes Evan Macedo to Our Leadership Team
 https://www.dfmurphy.com/wp-content/uploads/The-Value-of-Using-a-Virtual-Private-Network.jpg
628
1200
Wayne Texeira
https://dfmurphy.wpenginepowered.com/wp-content/uploads/Murphy-Insurance-Logo-Header.jpg
Wayne Texeira2026-09-01 21:08:272026-09-01 21:18:39The Value of Using a Virtual Private Network
 https://www.dfmurphy.com/wp-content/uploads/Password-Management-Best-Practices.jpg
628
1200
Wayne Texeira
https://dfmurphy.wpenginepowered.com/wp-content/uploads/Murphy-Insurance-Logo-Header.jpg
Wayne Texeira2026-08-20 07:00:052026-08-13 18:55:41Cybersecurity Essentials | Password Management Best Practices
 https://www.dfmurphy.com/wp-content/uploads/Man-looking-through-folder-scaled.jpg
1340
2560
Murphy Insurance
https://dfmurphy.wpenginepowered.com/wp-content/uploads/Murphy-Insurance-Logo-Header.jpg
Murphy Insurance2026-08-10 07:00:312026-06-26 15:01:52The Time Is Now to Kick-start Open Enrollment Efforts
 https://www.dfmurphy.com/wp-content/uploads/Certificates-of-Insurance-The-Costly-Mistakes-Many-Businesses-Dont-Catch-.jpg
628
1200
Murphy Insurance
https://dfmurphy.wpenginepowered.com/wp-content/uploads/Murphy-Insurance-Logo-Header.jpg
Murphy Insurance2026-07-30 07:00:472026-07-25 10:37:00Certificates of Insurance: The Costly Mistakes Many Businesses Don’t Catch
 https://www.dfmurphy.com/wp-content/uploads/Safe-Internet-Browsing-Practices.jpg
628
1200
Wayne Texeira
https://dfmurphy.wpenginepowered.com/wp-content/uploads/Murphy-Insurance-Logo-Header.jpg
Wayne Texeira2026-07-21 07:00:532026-07-20 12:12:15Safe Internet Browsing Practices
 https://www.dfmurphy.com/wp-content/uploads/Business-Interruption-Insurance-The-Coverage-That-Keeps-Your-Business-Alive-When-You-Cant-Open-Your-Doors-.jpg
628
1200
Murphy Insurance
https://dfmurphy.wpenginepowered.com/wp-content/uploads/Murphy-Insurance-Logo-Header.jpg
Murphy Insurance2026-07-14 07:00:212026-06-26 15:31:54Business Interruption Insurance: The Coverage That Keeps Your Business Alive When You Can’t Open Your Doors
 https://www.dfmurphy.com/wp-content/uploads/What-Counts-as-a-Home-Based-Business-.jpg
629
1200
Murphy Insurance
https://dfmurphy.wpenginepowered.com/wp-content/uploads/Murphy-Insurance-Logo-Header.jpg
Murphy Insurance2026-06-30 07:00:562026-06-26 14:40:30What Counts as a Home-Based Business (and When Your Home Policy Isn’t Enough)
Visit Our Business Insurance Page
Murphy Insurance stands as your steadfast partner in safeguarding your business from unforeseen challenges in today’s dynamic business landscape. In an era where comprehensive business insurance is not just a prudent choice but a vital one for ensuring the long-term stability and security of your enterprise, we are here to offer our expertise. Running a business inherently entails various risks that can potentially impact your financial stability and reputation. Learn more about our comprehensive business insurance solutions, which are meticulously designed to protect you from these potential threats, granting you peace of mind necessary to focus on the growth and prosperity of your business.
